Zero-Based Budgeting vs 50/30/20 Rule: Which Budgeting Method Is Right for You?
Managing your money becomes much easier when you have a clear system for deciding where your income should go. But with so many budgeting methods available, choosing the right one can be confusing.
Two of the most popular approaches are Zero-Based Budgeting (ZBB) and the 50/30/20 Budgeting Rule. Both are designed to improve money management, increase spending awareness, and help you make progress toward your financial goals. However, they approach budgeting very differently.
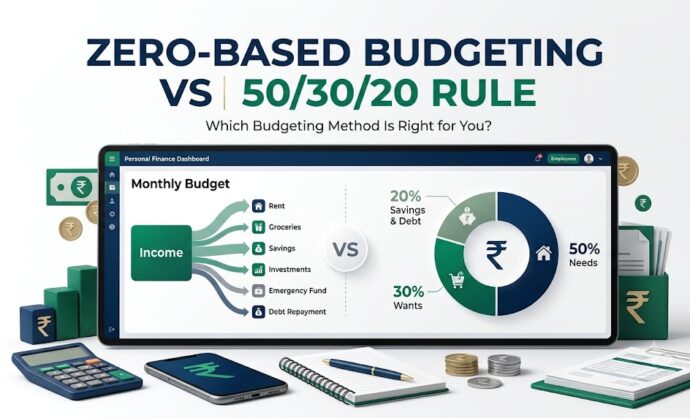
If you are researching Zero-Based Budgeting vs 50/30/20 Rule, the key difference is simple: zero-based budgeting assigns every rupee a specific purpose, while the 50/30/20 method divides income into three broad categories—needs, wants, and savings.
Neither approach has to be followed rigidly. Your income, expenses, debt, lifestyle, savings goals, and cost of living can all influence which budgeting method makes sense for you.
In this guide, we’ll compare both systems, explain how they work, look at their advantages and limitations, and show you how to create a personalized budgeting strategy.
What Is Zero-Based Budgeting?
Zero-Based Budgeting (ZBB) is a budgeting method where you assign your entire monthly income to specific expenses, savings, investments, or debt payments.
The objective is for your income minus all planned allocations to equal zero.
Income − Expenses − Savings − Investments − Debt Payments = ₹0
This is often referred to as Every-Dollar Budgeting. In India, you can think of it as every-rupee budgeting.
The important point is that zero does not mean you spend all your money.
If you earn ₹60,000 and allocate:
- ₹20,000 to essential expenses
- ₹10,000 to savings
- ₹8,000 to investments
- ₹7,000 to debt repayment
- ₹5,000 to an emergency fund
- ₹10,000 to discretionary expenses
your entire income has been assigned a purpose.
This creates greater financial control because you decide where your money goes before you start spending it.
How Zero-Based Budgeting Works
A typical zero-based budget starts with your after-tax income allocation.
Suppose your monthly take-home income is ₹60,000.
You could create the following spending categories:
| Category | Planned Amount |
|---|---|
| Rent | ₹15,000 |
| Groceries | ₹6,000 |
| Utilities | ₹3,000 |
| Transportation | ₹3,000 |
| Insurance | ₹2,000 |
| Entertainment | ₹2,000 |
| Eating Out | ₹2,000 |
| Emergency Fund | ₹5,000 |
| Investments | ₹8,000 |
| Debt Repayment | ₹7,000 |
| Short-Term Savings | ₹4,000 |
| Miscellaneous | ₹3,000 |
| Total | ₹60,000 |
Notice that the budget does not simply divide expenses into broad percentages.
Instead, it provides detailed instructions for every rupee.
This level of expense granularity is one of the biggest differences when comparing Zero-Based Budgeting vs 50/30/20 Rule.
Benefits of Zero-Based Budgeting
Zero-based budgeting can be particularly useful if you want to:
- Control overspending
- Identify unnecessary expenses
- Reduce wasteful spending
- Increase savings
- Accelerate debt repayment
- Build an emergency fund
- Track financial goals
- Improve cash flow management
It can also help you understand your spending habits.
For example, you may discover that eating out, shopping, subscriptions, or impulse purchases are consuming more money than expected.
Once these expenses are visible, you can make deliberate decisions about them.
ZBB Doesn’t Mean Eliminating Fun
Another misconception is that zero-based budgeting requires you to eliminate all discretionary spending.
It doesn’t.
You can allocate money for restaurants, entertainment, holidays, hobbies, or shopping.
The difference is that these expenses are planned.
If you allocate ₹3,000 for entertainment and spend ₹3,000, you’re following your plan.
If you allocate nothing and spend ₹7,000 impulsively, you’ve created a problem.
That distinction can make zero-based budgeting particularly useful for people struggling with overspending on wants.
What Is the 50/30/20 Budgeting Rule?
The 50/30/20 Budgeting Rule is a simpler percentage-based budgeting framework.
It divides your after-tax income into three broad groups:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
The 50% category generally includes essential expenses, such as:
- Rent
- Groceries
- Utilities
- Transportation
- Insurance
- Minimum debt payments
- Basic household expenses
The 30% category focuses on wants and discretionary spending, including:
- Dining out
- Entertainment
- Shopping
- Travel
- Hobbies
- Premium subscriptions
- Lifestyle purchases
The remaining 20% can be directed toward:
- Savings
- Emergency fund
- Investments
- Retirement savings
- Additional debt repayment
Example of the 50/30/20 Rule
Imagine you take home ₹60,000 per month.
A simplified plan could look like this:
| Category | Percentage | Amount |
|---|---|---|
| Needs | 50% | ₹30,000 |
| Wants | 30% | ₹18,000 |
| Savings/Debt | 20% | ₹12,000 |
| Total | 100% | ₹60,000 |
This is much simpler than creating dozens of individual spending categories.
That’s why the 50/30/20 method is often attractive for people who are new to budgeting for beginners.
Instead of tracking every transaction in detail, you monitor three broad areas.
Zero-Based Budgeting vs 50/30/20 Rule: Key Differences
Understanding Zero-Based Budgeting vs 50/30/20 Rule becomes easier when you compare them based on how they handle income, expenses, savings, and financial goals.
1. Level of Detail
Zero-based budgeting is highly detailed.
You might have separate categories for:
- Groceries
- Transportation
- Eating out
- Entertainment
- Shopping
- Insurance
- Investments
- Emergency savings
- Debt repayment
The 50/30/20 approach groups these expenses into broader categories.
For example:
Zero-Based Budgeting
- Groceries — ₹6,000
- Eating out — ₹2,000
- Entertainment — ₹2,000
- Shopping — ₹3,000
50/30/20
- Needs — ₹30,000
- Wants — ₹18,000
- Savings/Debt — ₹12,000
Therefore, ZBB provides more detailed financial tracking, while 50/30/20 prioritizes simplicity.
2. Ease of Use
The 50/30/20 system is relatively easy to understand.
You simply calculate your income and divide it into three categories.
Zero-based budgeting requires more work because you need to estimate individual expenses and allocate money across multiple categories.
For someone who enjoys spreadsheets and detailed planning, that may not be a problem.
For someone who finds budgeting tedious, a percentage-based system may be easier to maintain.
3. Financial Control
One of the major advantages of ZBB is detailed financial control.
If your monthly spending is higher than expected, you can identify exactly which category is responsible.
For example, if your grocery budget is ₹6,000 but actual spending reaches ₹9,000, you immediately have a category to investigate.
The 50/30/20 method may tell you that your overall needs are too high, but it may not reveal exactly where the additional spending occurred.
4. Budget Flexibility
Both methods can be flexible, but they handle changes differently.
With zero-based budgeting, you can make regular budget adjustments.
Suppose your electricity bill increases by ₹1,000. You could reduce another category by ₹1,000.
Similarly, if your income increases, you can allocate the additional money toward savings, investments, debt repayment, or lifestyle spending.
The 50/30/20 framework provides flexibility because the percentages themselves can be treated as guidelines rather than strict rules.
Your actual budget should reflect your circumstances.
5. Debt Repayment
If you have significant debt, ZBB can provide more control.
You can create a dedicated debt payoff strategy and determine exactly how much additional money should go toward your outstanding balances.
For someone pursuing aggressive debt repayment, detailed budgeting can make it easier to identify money that can be redirected toward debt.
The 50/30/20 framework can still include debt repayment within its savings/debt category, but it doesn’t provide the same level of detail.
6. Savings and Investments
Both methods can support savings and investments.
However, ZBB allows you to create individual allocations for different goals.
For example:
- Emergency fund — ₹5,000
- Vacation savings — ₹3,000
- Retirement savings — ₹5,000
- Mutual fund investment — ₹7,000
This makes it useful for goal-oriented budgeting.
The 50/30/20 system provides a broader savings target that you can divide according to your priorities.
Which Budgeting Method Should You Choose?
The right approach depends on your financial situation rather than simply following whichever method is more popular.
Zero-Based Budgeting May Suit You If:
You may prefer ZBB if:
- You frequently overspend.
- You have significant debt.
- Your income is limited.
- Your income changes from month to month.
- You have several financial goals.
- You want detailed expense tracking.
- You’re saving aggressively.
- You want more control over discretionary spending.
- You are working toward a specific financial target.
For example, imagine someone earning ₹70,000 per month while paying ₹25,000 toward multiple loans and EMIs.
A simple percentage framework may not provide enough detail.
A zero-based plan can identify how much can realistically go toward aggressive debt repayment while still covering essential expenses and maintaining savings.
50/30/20 May Suit You If:
The 50/30/20 framework may be easier if:
- You’re new to budgeting.
- Your income is stable.
- Your expenses are predictable.
- You don’t have major debt.
- You want a simple monthly spending plan.
- You don’t enjoy detailed financial tracking.
- You already have reasonable spending discipline.
It can also work as a starting point.
Once you become comfortable managing your money, you can move toward more detailed budgeting.
Why a Combined Budgeting Approach Can Work
When comparing Zero-Based Budgeting vs 50/30/20 Rule, you don’t necessarily have to select one method permanently.
A combined budgeting approach can use the simplicity of 50/30/20 while incorporating the detailed control of zero-based budgeting.
For example, someone earning ₹1,00,000 after tax might start with:
- 50% for needs
- 30% for wants
- 20% for savings, investments, and debt
Then they can break each category into individual allocations.
Needs
- Rent — ₹25,000
- Groceries — ₹7,000
- Transportation — ₹5,000
- Utilities — ₹3,000
- Insurance — ₹5,000
- Other essential expenses — ₹5,000
Wants
- Dining — ₹5,000
- Entertainment — ₹3,000
- Shopping — ₹5,000
- Travel — ₹7,000
- Hobbies — ₹3,000
- Miscellaneous — ₹7,000
Savings and Financial Goals
- Emergency fund — ₹5,000
- Retirement savings — ₹5,000
- Investment allocation — ₹7,000
- Additional debt repayment — ₹3,000
This approach provides a broad framework while still giving every rupee a purpose.
How to Create Your Own Monthly Budget
Regardless of which method you select, the following process can help you create a practical monthly spending plan.
Step 1: Calculate Your Take-Home Income
Start with your actual after-tax income.
If your salary is ₹80,000 after deductions, use ₹80,000 as the foundation of your budget.
Don’t build your spending plan around your gross salary.
Step 2: List Fixed Expenses
Start with fixed expenses, such as:
- Rent
- Loan EMI
- Insurance
- Internet
- School fees
- Subscriptions
These expenses are generally predictable.
Step 3: Estimate Variable Expenses
Next, calculate your variable expenses.
These might include:
- Groceries
- Electricity
- Fuel
- Dining
- Shopping
- Entertainment
Use previous bank statements or spending records to make realistic estimates.
Step 4: Account for Irregular Expenses
Don’t forget irregular expenses.
These may include:
- Annual insurance premiums
- Vehicle maintenance
- Festival shopping
- Annual subscriptions
- Travel
- Home repairs
- Unexpected expenses
One useful approach is to estimate the annual cost and divide it by 12.
For example, if you expect ₹24,000 of annual vehicle maintenance, allocate approximately ₹2,000 per month toward that future expense.
Step 5: Create an Emergency Fund
An emergency fund can help protect your budget from unexpected financial shocks.
Instead of relying on credit cards or loans when something goes wrong, you can use money specifically reserved for emergencies.
The appropriate amount depends on your income stability, essential expenses, dependents, insurance coverage, and other circumstances.
Step 6: Define Your Financial Goals
Your budget should do more than pay bills.
Identify your financial goals.
These might include:
- Building an emergency fund
- Paying off debt
- Buying a vehicle
- Buying a home
- Taking a vacation
- Building retirement savings
- Investing for long-term goals
Specific goals make saving more meaningful.
Step 7: Plan Your Investment Allocation
Once immediate priorities are addressed, decide how much money can be allocated toward investments.
Your investment allocation should reflect your financial goals, investment horizon, risk tolerance, and overall financial situation.
Separate short-term requirements from long-term wealth-building goals.
Step 8: Review Your Budget Every Month
A budget should not remain unchanged forever.
Review your actual expenses against your planned amounts.
If you consistently spend more on groceries, transportation, or utilities, adjust the relevant categories.
Likewise, if your income changes, update your budget.
This ongoing process is an important part of cash flow management.
Budgeting Tools You Can Use
You don’t need expensive software to manage your money.
Budget Spreadsheet
A budget spreadsheet is one of the simplest options.
You can create columns for:
- Date
- Income
- Expense
- Category
- Planned amount
- Actual amount
- Difference
A spreadsheet works particularly well for zero-based budgeting because you can create detailed categories and monitor every allocation.
Budgeting Apps
Budgeting apps can simplify expense tracking and financial monitoring.
Depending on the app and available integrations, you may be able to categorize transactions, track spending, monitor budgets, and review financial patterns.
However, technology isn’t the most important part.
Consistency is.
A simple spreadsheet used every month can be more useful than a sophisticated app that you stop using after two weeks.
Envelope Budgeting System
The envelope budgeting system is another practical approach.
Traditionally, people divide cash into envelopes for categories such as groceries, transportation, and entertainment.
Once an envelope is empty, spending in that category stops.
The same concept can be adapted digitally using separate categories or accounts.
This can be especially helpful for controlling discretionary spending.
Common Budgeting Mistakes to Avoid:Zero-Based Budgeting vs 50/30/20 Rule
Even a well-designed budget can fail when the assumptions behind it aren’t realistic.
Treating 50/30/20 as a Strict Rule
The 50/30/20 method should be viewed as a framework.
If your essential expenses are currently 60% or 65% of your income, forcing yourself to reduce them to exactly 50% may not be realistic.
Your housing costs, family responsibilities, location, income, and financial commitments matter.
Creating a Budget Without Tracking Spending
A plan is only useful if you compare it with reality.
Use bank statements, budgeting apps, or spreadsheets to track actual spending.
Ignoring Irregular Expenses
Annual and unexpected expenses can quickly disrupt a budget.
Plan for them in advance.
Making Your Budget Too Restrictive
If your budget gives you zero room for enjoyment, you may struggle to follow it consistently.
Reasonable discretionary spending can be included.
Forgetting Long-Term Goals
Don’t focus only on this month’s bills.
Your budget should also support long-term savings, investment, and retirement savings.
Ignoring Lifestyle Inflation
When income increases, spending often increases as well.
This is known as lifestyle inflation.
Instead of automatically increasing every expense, consider directing some additional income toward investments, savings, or debt repayment.
Zero-Based Budgeting vs 50/30/20 Rule: Comparison Table
| Factor | Zero-Based Budgeting | 50/30/20 Rule |
|---|---|---|
| Budgeting style | Detailed | Percentage-based |
| Level of detail | High | Moderate |
| Ease for beginners | Moderate | High |
| Expense tracking | Detailed | Broad |
| Spending control | High | Moderate |
| Savings planning | Highly customizable | Percentage-based |
| Debt repayment | Highly customizable | Included in savings/debt allocation |
| Financial goals | Highly customizable | General |
| Time required | Higher | Lower |
| Budget adjustments | Frequent when needed | Usually simpler |
| Best use | Detailed financial control | Simple money management |
The central distinction in Zero-Based Budgeting vs 50/30/20 Rule is therefore not simply the percentages.
It is the way each method makes you think about your money.
Zero-based budgeting asks:
“Where should every rupee go?”
The 50/30/20 method asks:
“How much of my income should go toward needs, wants, and savings?”
That difference can help you decide which framework better matches your personality and financial situation.
Also Read: Personal Loan in Delhi
Conclusion: Zero-Based Budgeting vs 50/30/20 Rule
The comparison between Zero-Based Budgeting vs 50/30/20 Rule ultimately comes down to your preferred level of control and simplicity.
Zero-based budgeting provides detailed planning. It can help you track individual expenses, control discretionary spending, reduce unnecessary costs, prioritize debt repayment, build savings, and work toward specific financial goals.
The 50/30/20 rule provides a simpler structure. By dividing income into needs, wants, and savings/debt, it gives beginners an easy starting point for managing their finances.
You can also combine both approaches.
Use the 50/30/20 framework to establish broad priorities and zero-based budgeting to assign specific amounts within those categories.
The most important thing isn’t whether your budget follows a perfect formula.
It’s whether your budget helps you live within your means, maintain financial control, prepare for unexpected expenses, and consistently move toward your goals.
Start with your actual income and expenses. Create realistic spending categories. Set savings goals. Account for irregular expenses. Review your spending every month and make adjustments when your financial circumstances change.
A successful budget isn’t about restricting your life.
It’s about giving your money a clear purpose.
FAQs: Zero-Based Budgeting vs 50/30/20 Rule
1. What is the difference between Zero-Based Budgeting and the 50/30/20 Rule?
Zero-Based Budgeting assigns every rupee of your income to a specific purpose, such as expenses, savings, investments, or debt repayment. The 50/30/20 Rule divides after-tax income into three broad categories: 50% for needs, 30% for wants, and 20% for savings and debt.
2. Is Zero-Based Budgeting better than the 50/30/20 Rule?
Neither method is universally better. Zero-Based Budgeting provides more detailed financial control, while the 50/30/20 Rule is simpler to understand and maintain. The appropriate method depends on your income, expenses, debt, financial goals, and budgeting preferences.
3. Can I use Zero-Based Budgeting and the 50/30/20 Rule together?
Yes. A combined approach can work well. You can use the 50/30/20 Rule as a high-level framework and then use Zero-Based Budgeting to assign specific amounts within each category.
4. Does Zero-Based Budgeting mean I have to spend all my money?
No. Zero-Based Budgeting means that every rupee is assigned a purpose. Money can be allocated to an emergency fund, investments, retirement savings, or debt repayment rather than being spent.
5. What does 50/30/20 mean in personal finance?
The traditional 50/30/20 framework suggests allocating approximately 50% of after-tax income toward needs, 30% toward wants, and 20% toward savings and debt repayment. These percentages can be adjusted according to individual circumstances.
6. Which budgeting method is better for beginners?
The 50/30/20 Rule is generally easier for budgeting beginners because it uses three broad categories. Once you become comfortable tracking your finances, you can introduce more detailed Zero-Based Budgeting.
7. Can Zero-Based Budgeting help me pay off debt faster?
Yes. Zero-Based Budgeting can identify money that can be redirected toward additional debt repayment. You can create a dedicated debt payoff strategy while continuing to cover essential expenses and other financial priorities.
8. How does Zero-Based Budgeting help reduce unnecessary expenses?
By assigning specific amounts to individual spending categories, Zero-Based Budgeting makes spending patterns more visible. This can help you identify subscriptions, impulse purchases, excessive dining, and other unnecessary expenses.
9. Should savings be included in Zero-Based Budgeting?
Yes. Savings should be treated as a planned allocation rather than whatever money happens to remain at the end of the month. You can create separate allocations for an emergency fund, short-term savings, long-term savings, and other financial goals.
10. What should I do if my expenses don’t fit the 50/30/20 Rule?
Don’t force your finances into the percentages. Housing costs, family responsibilities, debt, location, and income can make the traditional split unrealistic. Review your essential expenses and create a personalized budgeting strategy that reflects your actual circumstances.
11. Can I use a spreadsheet for Zero-Based Budgeting?
Yes. A budget spreadsheet can track income, planned expenses, actual expenses, savings, investments, debt payments, and differences between planned and actual spending. It is particularly useful when you want detailed expense tracking.
12. What is the main goal of personal budgeting?
The main goal is to give your income a clear purpose while helping you manage expenses, build savings, handle debt, prepare for unexpected expenses, and work toward your financial goals. The best budgeting system is one that you can realistically maintain over time.
Follow On Instagram